

Tata Sons Board Backs Chandrasekaran Despite Trusts Rift
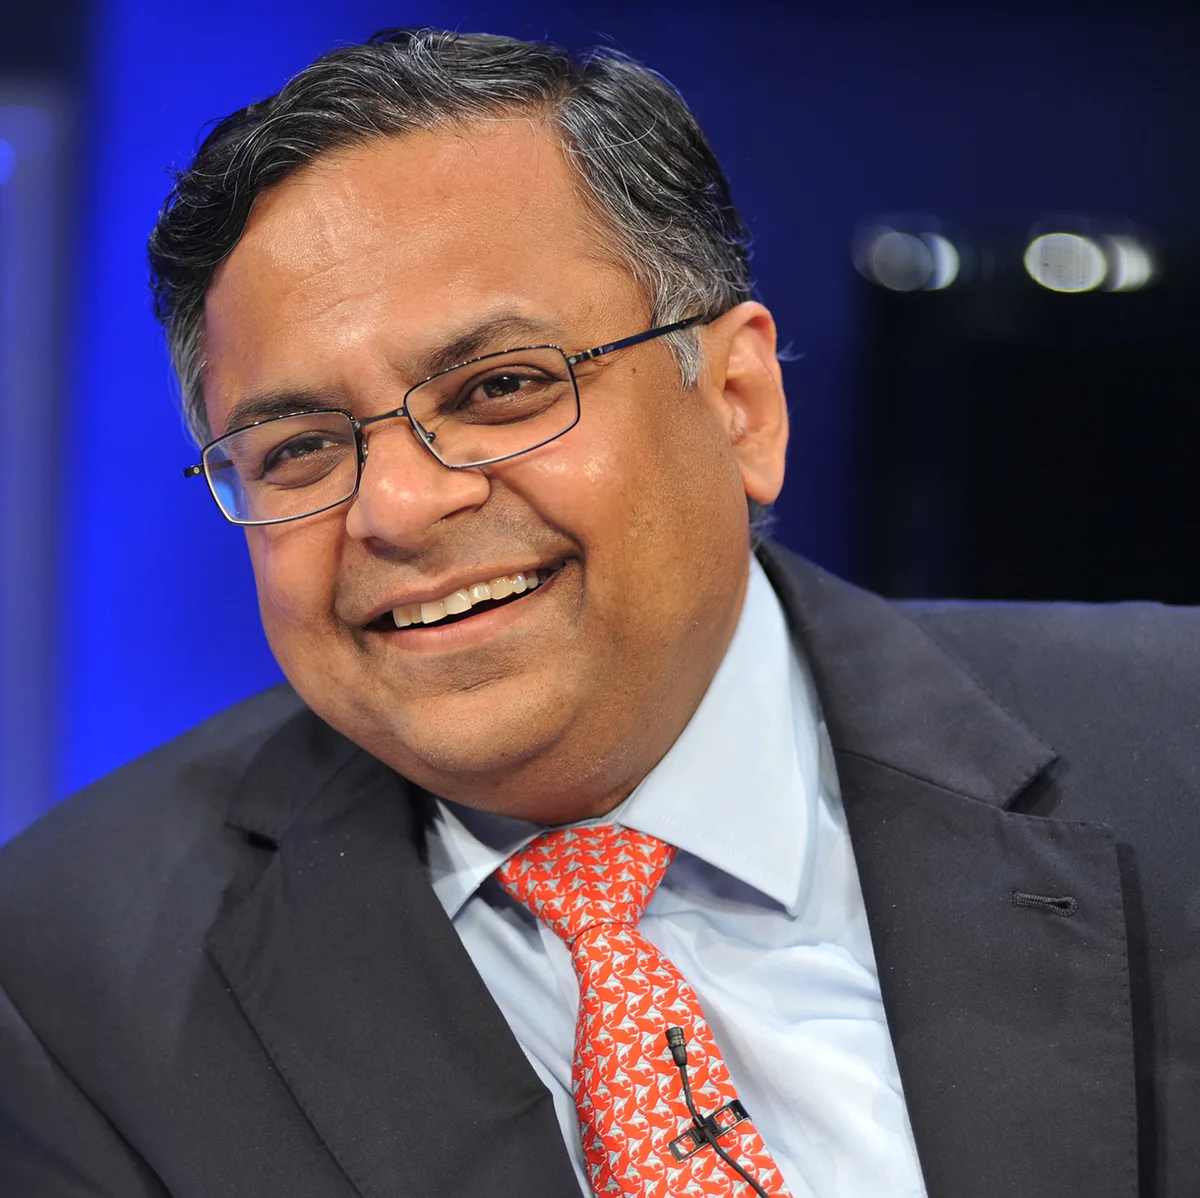
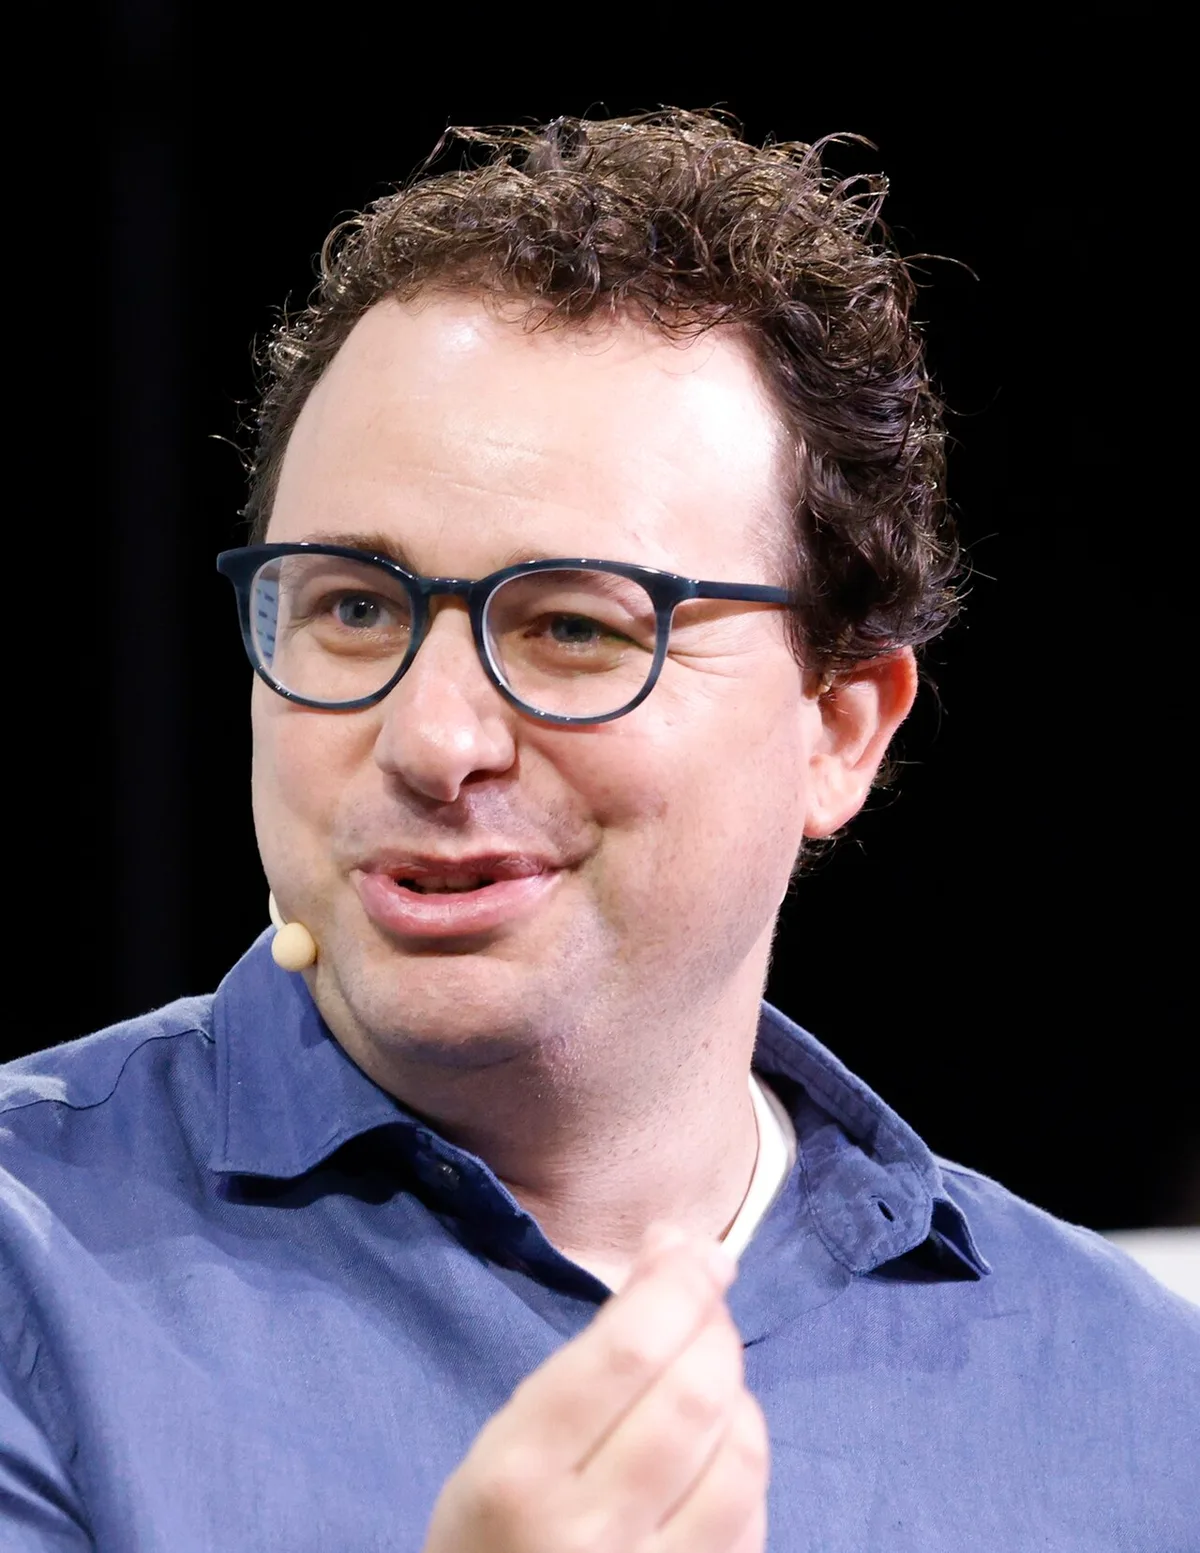
The Tata Sons board met in Mumbai on September 17, 2026, and approved a fresh five-year term for N Chandrasekaran as executive chairman. Noel Tata voted against the reappointment resolution. It carried by majority.
The vote reversed the course Chandrasekaran had set only weeks earlier. On August 12 he had announced he would not seek reappointment once his tenure ended on February 20, 2027. He had failed to get unanimous support from the board. His statement set the exit in plain language.
“I have completed 40 years of professional life at the Tata Group. I am grateful for the immensely satisfying opportunity to contribute to this venerable institution.”
“I have decided not to offer myself for reappointment when my term ends on February 20, 2027.”
Forty years. That single number framed the rest. The February date was no longer a routine term end; it was the deadline he had chosen himself. The succession question for the holding company of India’s largest business group opened at once.
Tata Sons, headquartered in Mumbai, owns the bulk of shareholding in the group’s affiliate companies, along with land holdings, tea estates and steel plants, and draws its revenue from their dividends. About 66 percent of its equity capital is held by philanthropic trusts endowed by members of the Tata family. The Shapoorji Pallonji Group holds about 18.37 percent. Those two blocks framed every later vote.
Chandrasekaran had taken the chair on 21 February 2017, becoming the first non-Parsi and professional executive to head the group. A new five-year term would keep him well beyond the exit date he had already named.
What made the September decision land with force was its speed. The same board that had received his decision not to offer himself again now moved to keep him. On September 3 the Nomination and Remuneration Committee, the body that weighs appointments at the top, met and unanimously asked him to reconsider. The request rested on his contributions and the larger interests of the Tata Group. Less than a month after he had taken himself out of the running, the same leadership machinery asked him back in.
An unnamed spokesperson for the Sir Dorabji Tata Trust stated the position without softening.
“Please note that there is no change in the stand taken by SDTT (Sir Dorabji Tata Trust) in its board meeting held on 13th August 2026, respecting the decision of Mr Chandrasekaran to not offer himself for reappointment and seeking initiation of steps for appointment of a new chairman, as communicated by the SDTT to the company secretary, Tata Sons on the same day.”

Before the board sat, the Sir Dorabji Tata Trust moved to keep Venu Srinivasan out of listing-related discussions and voting. Srinivasan refused. He cited his statutory and fiduciary duties as a director and would not step aside.
Tata Sons had already put the case for continuity on the record. The board had received from Tata Trusts their unanimous resolution dated July 28, 2025. The company statement set the language out in full.
“The Board received from Tata Trusts their unanimous resolution dated July 28, 2025 expressing their appreciation of the Chairman of Tata Sons, Mr. N. Chandrasekaran (Chandra) for his stewardship of the Group from 2017 onwards. In recognition of these efforts the Tata Trusts resolved that he be re-appointed as Executive Chairman for a further term of five years upon the expiry of his current term.”
That stewardship had already been tested in court. In December 2019 the National Company Law Appellate Tribunal declared Chandrasekaran’s appointment illegal and ordered the restoration of Cyrus Mistry. On 10 January 2020 a Supreme Court bench of Chief Justice Sharad Arvind Bobde and Justices B. R. Gavai and Surya Kant stayed the NCLAT order. The bench was direct.
“We find there are lacunae in the judicial orders passed by the NCLAT.”
The stay held. On 26 March 2021 the Supreme Court upheld Tata Sons’ decision to remove Mistry. The chairmanship the Trusts later praised had survived that challenge. By the time the board met again in 2026, the same role faced pressure of a different kind.
On September 11 the Reserve Bank of India rejected Tata Sons’ request to surrender its registration as a core investment company. The holding company had applied in March 2024 after repaying more than Rs 21,000 crore of debt, a sum meant to free it from the rules that forced a public listing. In 2022 the RBI had placed Tata Sons in the upper layer of non-banking financial companies. An upper-layer NBFC is a non-bank firm judged systemically important enough that the central bank requires a stock-market listing within three years. A core investment company is a non-banking financial firm whose main business is holding equity in group companies rather than making loans to the public. Surrendering that status would have taken Tata Sons out of the upper-layer framework altogether. The rejection closed the exit. Following the September 11 decision, the board initiated and discussed steps toward a stock-market listing.
In August 2026 the Tata Sons annual general meeting was adjourned for lack of quorum, a first in the company’s history. The two main Tata Trusts could not jointly nominate a representative. An annual general meeting is the yearly gathering of shareholders that must confirm major board resolutions before those resolutions become binding. Both the reappointment and the steps toward listing still required that confirmation.
The Registrar of Companies reset the outer limit. The deadline to convene the AGM was extended to December 31, 2026. Tata Sons now had the balance of the year to assemble the meeting, restore quorum, and put the board’s resolutions to a shareholder vote. Until that day arrived and the room filled, neither path could be completed.
December 31, 2026, remained the deadline hanging over Bombay House.